Service
Wealth Management
A portfolio built for a life in two tax systems.
First call free · CISI Associate Member
In shortWhat it is, who it is for, how it works
A portfolio built to operate from where you actually live, rather than a UK playbook that no longer fits. It is for mobile professionals, recent UK leavers and retirees with cross-border assets. The work covers custody on platforms that accept Thailand-resident clients, currency-aware asset allocation, and the long-term cost of fees.
Who this is forThe situations this work starts from
- 1
Mobile professionals with cross-border portfolios
Have investment accounts in multiple jurisdictions and want them coherently managed against a cross-border life.
- 2
Retirees seeking discretionary management
Want professional portfolio management aligned to a sustainable drawdown plan.
- 3
Recent UK leavers
Were using a UK-domestic platform that no longer accepts non-resident contributions, need an expat-friendly alternative.
What is involvedThe detail behind the decision
The default UK wealth-management playbook does not survive contact with cross-border life. Your platform may stop accepting contributions; your ISA may stop being efficient; your domestic broker may quietly transfer your account to a non-resident desk. The work is building a portfolio that operates from where you actually live.
Custody arrangements that survive residency
Some platforms onboard Thailand-resident clients; many quietly do not. Custody choice matters more than asset allocation for the expat client.
Currency-aware asset allocation
A GBP-heavy portfolio for a retiree spending in THB is a currency bet, not a diversified strategy. The portfolio needs to be sized against the currency of expenditure.
Pension fee calculatorFree, two minutes, no sign-up
Common mistakesAnd how the work avoids them
- 01
Holding a portfolio with a UK broker that no longer accepts you
Many UK platforms have quietly stopped accepting non-resident contributions or new positions. You may find this out only when you try to act. The fix is checking now, not later.
- 02
Ignoring fee compounding
The difference between a 0.45% pa platform and a 1.5% pa platform is six figures over a typical retirement horizon. The work includes the fee audit.
Two meetings, then a written planThe first two are free
- 1
Initial call
30 minutes, free
- 2
Fact-find meeting
Your full financial position, free
- 3
Written report
£250, prepared for you
- 4
Report meeting
Findings and recommendations
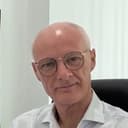


Richard Knight, ACSI
Senior Consultant, Business Class Asia
CISI Associate Member · Vice Chair, British Chamber of Commerce, Hua Hin · 15+ years in private wealth
What clients sayPublished on LinkedIn
Fees and how I am paidEvery cost in writing, before you decide
I am paid through commission on the products arranged and an ongoing fee on the assets managed. Every cost, and what it pays, is set out in writing before you decide.
You may ask what any recommendation pays me, and the figures that apply are agreed in writing in the engagement letter before you proceed.
A first 30-minute consultation costs nothing and obliges you to nothing.
Client assets are held by an appointed trustee or a regulated platform, never by me.
QuestionsAbout Wealth Management
Further readingFor a first read before a call